Founders and early employees who intend to build, fund or join high-growth companies must master a compact vocabulary that governs ownership, governance and survival. The third instalment in this primer explains cap tables, SAFEs and convertible instruments, runway and burn, dilution mechanics, and the basic architecture of liquidation preferences and vesting — terms that shape who keeps control and who gets paid when things go right or wrong.
Cap tables: the ledger that matters
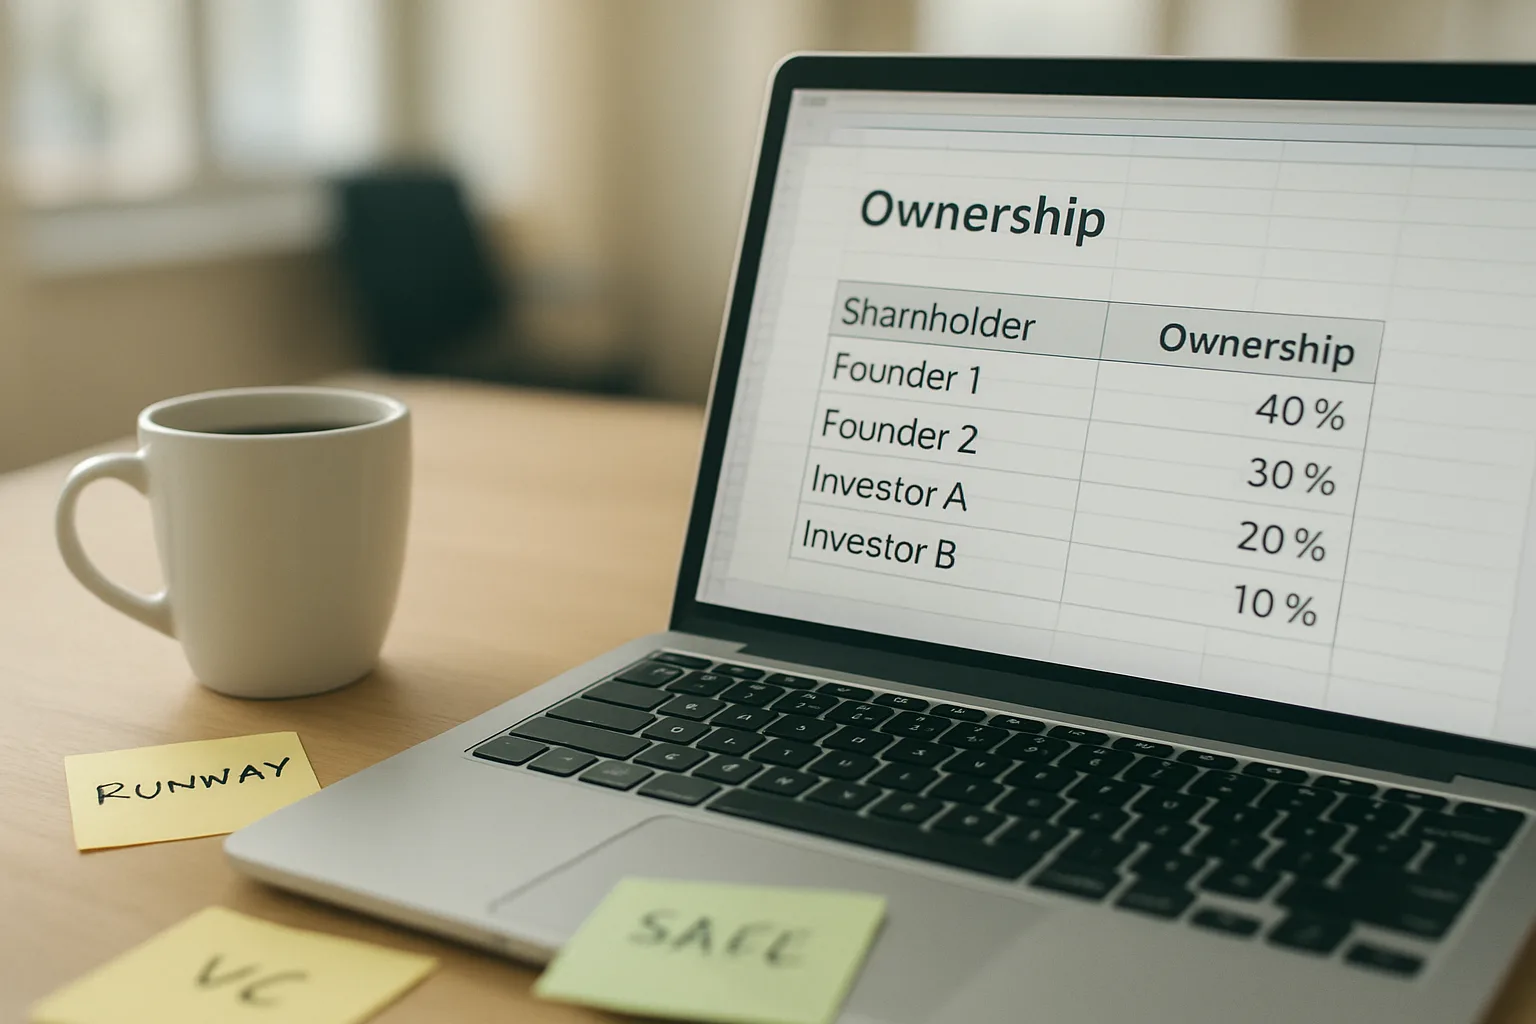
The capitalization table, or cap table, is the definitive record of who owns what: founders, investors, option pools and sometimes advisers. It shows share counts, classes of stock, ownership percentages, fully diluted percentages and key conversion rights. For every financing round, managers and lawyers update the cap table to reflect new issuances and changes to option pools.
An accurate cap table is essential for several reasons. It determines voting power and board composition, it underpins valuation math used in term sheets, and it is the baseline for modelling future dilution. Mistakes or omissions can produce surprising outcomes for founders and employees at liquidation or in subsequent financings.
SAFEs, convertibles and the timing of dilution
Simple Agreements for Future Equity (SAFEs) and convertible notes are common in seed-stage financings because they postpone the need to set a valuation. These instruments provide investors with a contractual right to receive equity at a later equity financing, typically at a discount or with a valuation cap.
Critically, SAFEs and convertible notes do not create ownership until they convert. That conversion usually happens at a priced equity round and can substantially alter the cap table depending on valuation, cap terms and whether the instruments include discounts or pro rata rights. Founders should model conversion mechanics across multiple scenarios to see how much of the company will be owned by early investors once a priced round occurs.
Runway and burn — the company’s operational clock
Runway is a simple but pivotal metric: the number of months a company can continue operations at its current cash burn rate before running out of money. Burn is typically measured as net cash outflows per month (cash spent minus cash received). Together, burn and runway determine the urgency and leverage a founder has when approaching investors.
Founders often seek to hit specific milestones before raising the next round to maximise valuation and minimise dilution. That means accurately projecting expenses, hiring plans and revenue to avoid emergency fundraises, which tend to be more dilutive and may carry less favourable terms.
Dilution mechanics: percentages, option pools and anti-dilution
Dilution is the reduction in existing shareholders’ percentage ownership resulting from the issuance of new shares. It is an arithmetic outcome of issuing additional equity: a founder who owns 40% will own a smaller share after a new investor takes 20% of the expanded equity pool.
Several levers affect how dilution unfolds. Pre-money versus post-money definitions determine whether the option pool is sized before or after the valuation is applied — a commonly negotiated point in term sheets. Anti-dilution protections, often granted to investors, can adjust conversion rates if the company later issues shares at a lower valuation (a “down round”); these protections can be full-ratchet or weighted-average and have very different impacts.
Founders should build dilution schedules into their financial modelling, showing ownership percentages after common fundraising scenarios. Small differences in how instruments are structured can lead to large changes in control and economic outcomes.
Liquidation preferences and distribution waterfalls
Liquidation preferences govern who gets paid first when a company is sold or liquidated. Typical seed-stage investors ask for a 1x liquidation preference, meaning they receive their invested capital back before common shareholders share proceeds. Preferences can be participating or non-participating; a participating preference lets an investor get their capital back and then share in remaining proceeds pro rata, which can significantly reduce what is left for founders and employees.
Term sheets may also include multiples (e.g., 2x) or seniority between classes of investors. These clauses determine distribution waterfalls and can turn a headline valuation into a very different economic reality at exit.
Investors and founders should agree on how exit proceeds will flow before headline valuation is set, because preferences and participation change the effective payout materially.
Vesting: incentives and departures
Vesting schedules align long-term incentives by spreading the right to own shares over time. Standard vesting for founders and employees in many markets is a four-year schedule with a one-year cliff; that means no shares vest until the one-year mark, after which monthly or quarterly vesting begins.
Acceleration clauses — single or double-trigger — affect how options vest on events such as acquisition or termination. These provisions are often heavily negotiated because they influence founder retention, acquisition dynamics and employee protections.
Practical steps founders and employees should take
- Maintain a clean, up-to-date cap table and model multiple fundraising scenarios.
- Understand whether instruments are pre-money or post-money and how that affects the option pool sizing.
- Run sensitivity analyses showing ownership and payout outcomes under different valuations, liquidation preference structures and anti-dilution provisions.
- Monitor runway monthly and plan fundraises well before it becomes urgent to preserve valuation leverage.
- Ensure compensation packages and vesting schedules are clear to attract and retain talent while protecting founders’ long-term equity.
Mastering these terms does not guarantee fundraising success, but it provides the frameworks founders and early employees need to make reasoned decisions about dilution, control and exit economics. For many startups, understanding the arithmetic behind ownership and the timing of conversion events is as important as the product or market strategy when it comes to surviving the early years and rewarding those who build the business.
Sources & further reading